Insolvency & Bankruptcy
Avoidance Transactions Under the Insolvency and Bankruptcy Code
An examination of preferential, undervalued, fraudulent and extortionate transactions under the Insolvency and Bankruptcy Code, including investigation and remedies before the Adjudicating Authority.
On this page
Introduction
The commencement of a corporate insolvency resolution process does not limit the resolution professional’s role to collecting claims and managing the corporate debtor as a going concern. The resolution professional must also examine transactions entered into before the insolvency commencement date to determine whether value was improperly transferred, particular creditors were preferred or the business was carried on in a manner prejudicial to creditors.
The Insolvency and Bankruptcy Code, 2016 addresses such conduct through provisions concerning preferential transactions, undervalued transactions, transactions intended to defraud creditors, extortionate credit transactions and fraudulent or wrongful trading. These provisions do not merely punish past misconduct. Their principal purpose is to restore value to the insolvency estate and protect the collective interests of creditors.
Key Considerations
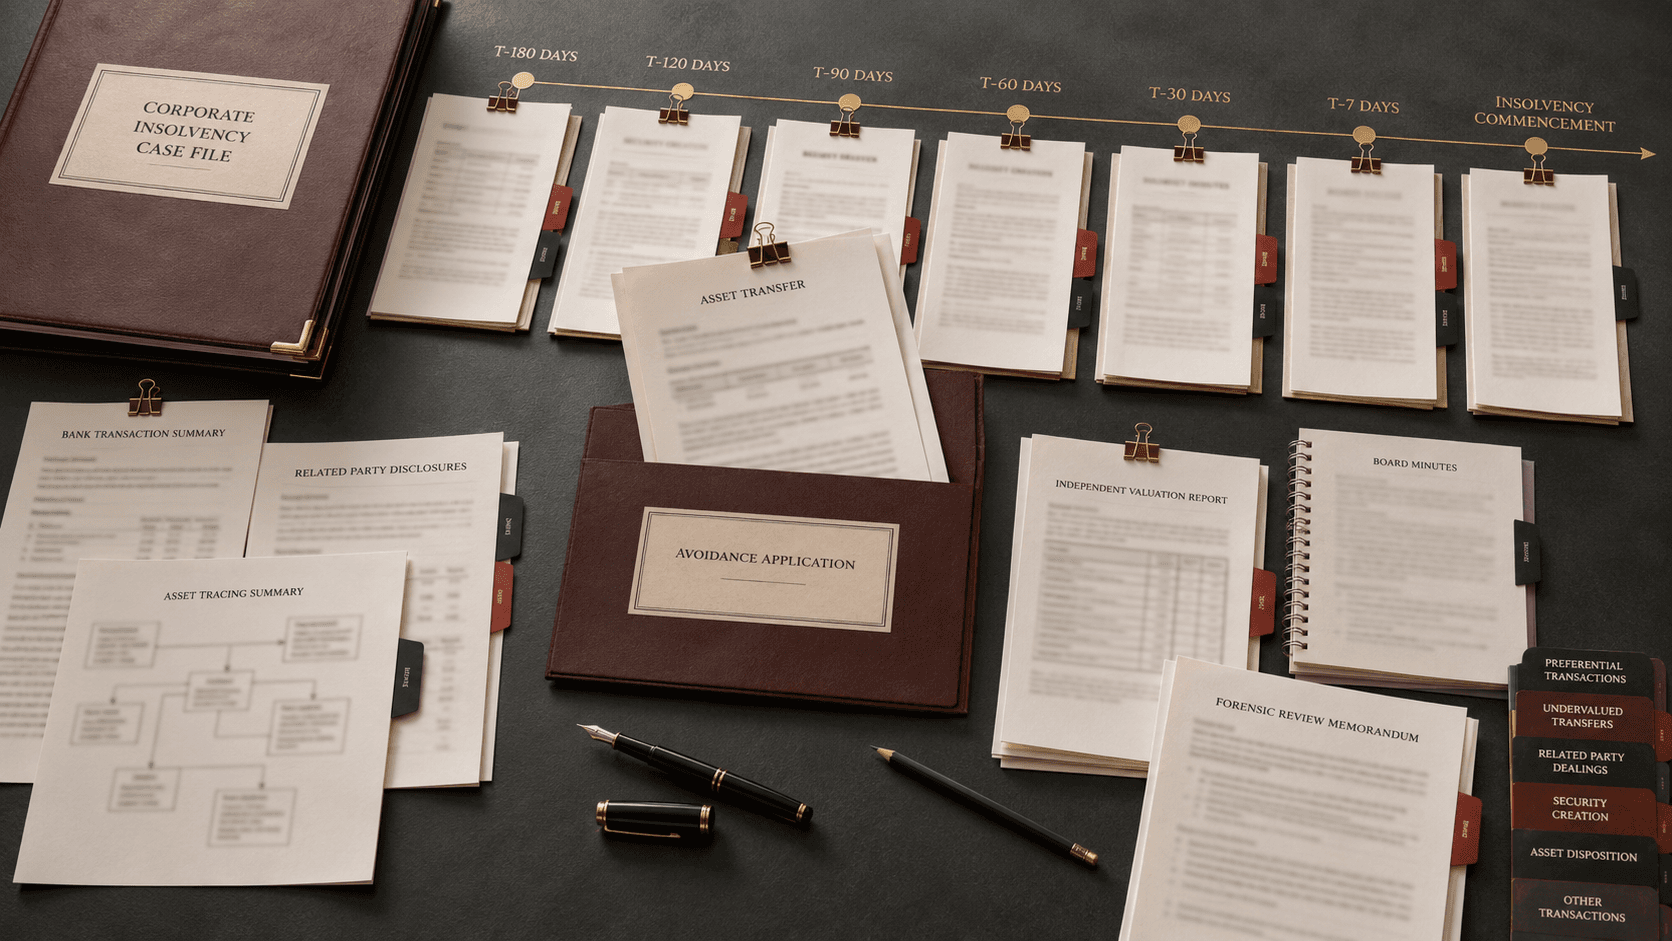
An avoidance review should begin with a detailed examination of the corporate debtor’s financial affairs before the insolvency commencement date. The resolution professional ordinarily requires access to books of account, bank statements, statutory records, related-party disclosures, security documents, asset registers, board minutes and material commercial agreements.
Particular attention should be given to transactions that:
- transferred assets to promoters, directors or related entities;
- created security for an existing liability shortly before insolvency;
- accelerated payments to selected creditors;
- released or compromised substantial receivables;
- involved the sale of assets below their apparent value;
- imposed unusually onerous financing terms;
- diverted business or revenue to connected entities; or
- were unsupported by adequate commercial documentation.
Not every transaction that disadvantages the corporate debtor is avoidable. Each category under the Code has separate statutory requirements. A transaction must therefore be examined under the correct provision rather than being generally characterised as suspicious or detrimental.
The Supreme Court has emphasised that the elements of a preferential transaction under Section 43 must be determined by applying the statutory requirements contained in that section. Commercial intent or the absence of dishonest motive does not, by itself, decide whether a transaction constitutes a deemed preference.
Preferential Transactions
Section 43 addresses transactions through which the corporate debtor gives a preference to a creditor, surety or guarantor in respect of an antecedent financial debt, operational debt or other liability.
A transaction may constitute a preference where it has the effect of placing the beneficiary in a more advantageous position than it would have occupied if the corporate debtor’s assets were distributed under Section 53 of the Code. The provision is concerned with the effect of the transaction and the statutory relationship between the corporate debtor, the antecedent liability and the beneficiary.
The relevant look-back period is:
- two years preceding the insolvency commencement date for a transaction involving a related party, other than one related solely by reason of employment; and
- one year preceding the insolvency commencement date for a transaction involving a person who is not a related party.
The Code excludes certain transactions from the preference provision. These include transfers made in the ordinary course of the business or financial affairs of the corporate debtor or the transferee, as well as certain security interests securing new value, subject to the statutory conditions.
The ordinary-course exception requires a fact-sensitive inquiry. Merely describing a transaction as routine or recording it through normal accounting entries does not necessarily establish that it occurred in the ordinary course. The nature, timing, commercial justification and historical pattern of similar transactions should be examined.
In Anuj Jain, Interim Resolution Professional for Jaypee Infratech Limited v. Axis Bank Limited, the Supreme Court explained the analytical steps required under Section 43. The decision also distinguished between a creditor of the corporate debtor and a lender whose debt was owed by another entity, despite the corporate debtor having provided security over its assets.
Where a preference is established, the Adjudicating Authority may pass restorative orders under Section 44. These may include vesting transferred property in the corporate debtor, releasing or discharging security interests, directing repayment of benefits received and restoring the position that would have existed without the preference.
Undervalued Transactions
Sections 45 and 46 address transactions in which the corporate debtor makes a gift or transfers assets for consideration whose value is significantly lower than the value provided by the corporate debtor.
A transaction is not undervalued merely because it later appears commercially unsuccessful. The relevant issue is whether the corporate debtor transferred value without receiving reasonably equivalent consideration at the time of the transaction.
The look-back period for an undervalued transaction is:
- two years preceding the insolvency commencement date where the transaction involved a related party; and
- one year preceding the insolvency commencement date where the transaction involved another person.
The provision excludes transactions entered into in the ordinary course of business. A genuine sale of obsolete inventory at a reduced price, for example, may require a different assessment from the transfer of a productive asset to a promoter-controlled entity without a credible valuation or payment trail.
The review should consider:
- independent valuations available at the relevant time;
- the method used to determine consideration;
- the relationship between the parties;
- whether the consideration was actually received;
- the financial condition of the corporate debtor;
- the purpose recorded for the transaction; and
- whether comparable transactions were undertaken with independent parties.
Where the resolution professional or liquidator does not report an undervalued transaction, a creditor, member or partner may apply to the Adjudicating Authority under Section 47, subject to the statutory requirements. This provides an additional safeguard where those responsible for investigating the corporate debtor’s affairs fail to act.
If an undervalued transaction is established, the Adjudicating Authority may restore the position that existed before the transaction and protect the interests of persons who are victims of it. The available orders may include requiring property to be vested in the corporate debtor, releasing security, requiring payment of benefits received or modifying the terms of the transaction.
Transactions Defrauding Creditors
Section 49 applies to an undervalued transaction deliberately entered into to keep assets beyond the reach of persons entitled to make claims against the corporate debtor or to prejudice their interests in relation to such claims.
Unlike an ordinary undervalued transaction, Section 49 contains an additional element concerning the purpose for which the transaction was undertaken. The surrounding circumstances may therefore become particularly important.
Relevant indicators may include:
- transfer of valuable assets immediately before anticipated enforcement;
- movement of assets to a newly created related entity;
- retention of control or use after the purported transfer;
- absence of genuine consideration;
- false or incomplete transaction records;
- unusual urgency without commercial justification; and
- concealment of the transaction from lenders, auditors or stakeholders.
The Adjudicating Authority may pass orders restoring the position that existed before the transaction and protecting the interests of persons prejudiced by it. The Code also recognises protection for certain persons who acquired interests in good faith, for value and without notice of the relevant circumstances.
A finding under Section 49 should be based on evidence rather than suspicion arising solely from proximity to insolvency. The application should identify the assets transferred, the parties involved, the consideration, the surrounding circumstances and the manner in which creditors were intended to be prejudiced.
Extortionate Credit Transactions
Sections 50 and 51 deal with extortionate credit transactions entered into during the two years preceding the insolvency commencement date.
A credit transaction may be examined where its terms require the corporate debtor to make exorbitant payments or are unconscionable under the principles of contract law. The purpose of these provisions is not to reopen every expensive or high-risk loan. The terms must satisfy the statutory standard of being extortionate.
The applicable regulations may exclude certain debt extended by persons providing financial services in compliance with law. Therefore, the identity and regulatory status of the lender, as well as the legal framework governing the transaction, should be verified before alleging that the facility was extortionate.
The review may consider:
- the interest rate and manner of compounding;
- default interest and penal charges;
- disproportionate fees or deductions;
- the value of security obtained;
- repayment obligations compared with the amount advanced;
- the corporate debtor’s financial vulnerability when the facility was granted; and
- whether the terms had any credible commercial justification.
Where the Adjudicating Authority finds that a credit transaction was extortionate, it may restore the parties to their prior position, set aside or modify the debt, require repayment, relinquish security interests or direct the return of benefits received.
Fraudulent and Wrongful Trading
Section 66 deals with fraudulent trading and wrongful trading. Although commonly considered alongside avoidance transactions, the provision is directed toward the conduct of persons responsible for the corporate debtor’s business and may result in personal contribution orders.
Under Section 66(1), where the business of the corporate debtor has been carried on with intent to defraud creditors or for a fraudulent purpose, the Adjudicating Authority may direct persons who knowingly participated in carrying on the business in that manner to contribute to the assets of the corporate debtor.
Fraudulent trading requires more than poor management, commercial misjudgment or an unsuccessful business strategy. The application must establish the fraudulent purpose and the person’s knowing participation.
Section 66(2) concerns directors or partners who knew, or ought to have known, before the insolvency commencement date that there was no reasonable prospect of avoiding the commencement of the corporate insolvency resolution process and who failed to exercise due diligence in minimising potential loss to creditors.
Whether due diligence was exercised is assessed with reference to the standards of a reasonably diligent person possessing both:
- the general knowledge, skill and experience reasonably expected of a person carrying out the same functions; and
- the actual knowledge, skill and experience of the director or partner concerned.
The wrongful-trading provision does not impose automatic liability whenever a company enters insolvency. The timing of the person’s knowledge, the availability of realistic restructuring options and the steps taken to minimise creditor losses must be carefully evaluated.
Investigation and Application before the Adjudicating Authority
The resolution professional has a statutory duty to file applications for avoidance of transactions in accordance with Chapter III of Part II of the Code. The investigation should be commenced early because the relevant transactions may involve extensive records, multiple entities and complex fund flows.
A properly prepared application should ordinarily identify:
- the statutory category relied upon;
- the transaction and the parties involved;
- the relevant look-back period;
- the assets, funds or benefits transferred;
- the antecedent debt or liability, where relevant;
- the relationship between the parties;
- the effect on the insolvency estate or creditors;
- the evidence supporting each statutory element; and
- the specific relief sought from the Adjudicating Authority.
Forensic reports may assist the investigation, but the resolution professional should independently apply the statutory tests. An allegation should not rest solely on a broad observation in an auditor’s report where the underlying documents do not establish the necessary ingredients.
Avoidance proceedings serve a purpose distinct from determination of claims or approval of a resolution plan. Their objective is to reverse the effect of transactions or require contributions that restore value to the corporate debtor. The treatment of pending avoidance applications should therefore be expressly addressed in the resolution plan and related process documents, including who will pursue the applications and how any recoveries will be distributed, subject to the Code and approval of the Adjudicating Authority.
Conclusion
Avoidance provisions are an essential part of the insolvency framework because they prevent the period preceding insolvency from being used to favour selected parties, remove assets from the estate or impose unfair liabilities on the corporate debtor.
Effective investigation requires more than identifying transactions that appear commercially unfavourable. The resolution professional must classify each transaction under the correct statutory provision, establish every required element and support the application with a clear documentary and financial record.
For creditors and prospective resolution applicants, avoidance proceedings may materially affect the value available in the insolvency process. Their treatment should therefore be considered when evaluating the corporate debtor, formulating a resolution plan and assessing potential recoveries.
The effectiveness of an avoidance review depends on early investigation, correct statutory classification and evidence capable of establishing the transaction and the relief sought.
This article provides a general overview and does not constitute legal advice. The Insolvency and Bankruptcy Code, applicable regulations and judicial decisions should be reviewed in light of the facts and the law prevailing at the relevant time.
Discuss a related matter
ASR LAW advises clients on commercial disputes, financial enforcement, arbitration, insolvency and intellectual-property matters.
Contact the Firm