DRT & SARFAESI
Enforcement Strategy Under the SARFAESI Act
A practical overview of enforcement strategy under the SARFAESI Act, including classification, demand notice, possession, sale procedure and remedies before the Debts Recovery Tribunal.
On this page
Introduction
The Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002 provides secured creditors with a statutory mechanism to enforce security interests without first obtaining a decree from a court or tribunal. The process, however, is not automatic. Each stage—from classification of the account to possession and sale—must comply with the Act, the Security Interest (Enforcement) Rules, 2002, the applicable regulatory framework and the underlying security documents.
A successful enforcement strategy therefore requires more than the issuance of statutory notices. The secured creditor must establish that the debt, the security interest and the enforcement action are legally sustainable, commercially appropriate and supported by a complete documentary record.
Key Considerations
Before commencing enforcement, the secured creditor should undertake a comprehensive review of the facility and security documents. This ordinarily includes verifying the identity of the borrower and guarantors, the amount outstanding, the occurrence of default, the validity and enforceability of the security documents, the description of the secured assets and the authority of the officer proposing to act.
Registration of the security interest with the Central Registry is particularly important. Section 26D restricts a secured creditor from exercising enforcement rights under Chapter III unless the security interest has been registered with the Central Registry. Registration also assumes significance for determining priority under Section 26E, subject to the Insolvency and Bankruptcy Code, 2016 and other applicable statutory qualifications.
The creditor should also confirm that the transaction and the secured asset fall within the scope of the Act. Section 31 excludes certain categories, including pledges of movable property, security interests created in agricultural land, financial assets not exceeding the prescribed statutory threshold and cases in which the amount due is below twenty per cent of the principal amount and interest. The nature and actual use of the secured property should therefore be examined rather than relying only on its description in the title documents.
Where more than one secured creditor has financed the asset, enforcement must be considered in light of Section 13(9). Subject to the Insolvency and Bankruptcy Code, enforcement under Section 13(4) ordinarily requires the consent of secured creditors representing not less than sixty per cent in value of the outstanding amount as on the relevant record date.
The creditor should additionally investigate pending insolvency proceedings, attachments, tenancy claims, statutory dues, litigation affecting title and prior encumbrances. These issues may not always prevent enforcement, but they may affect possession, priority, valuation, marketability and the representations that must be made to prospective purchasers.
Issuance of the Demand Notice
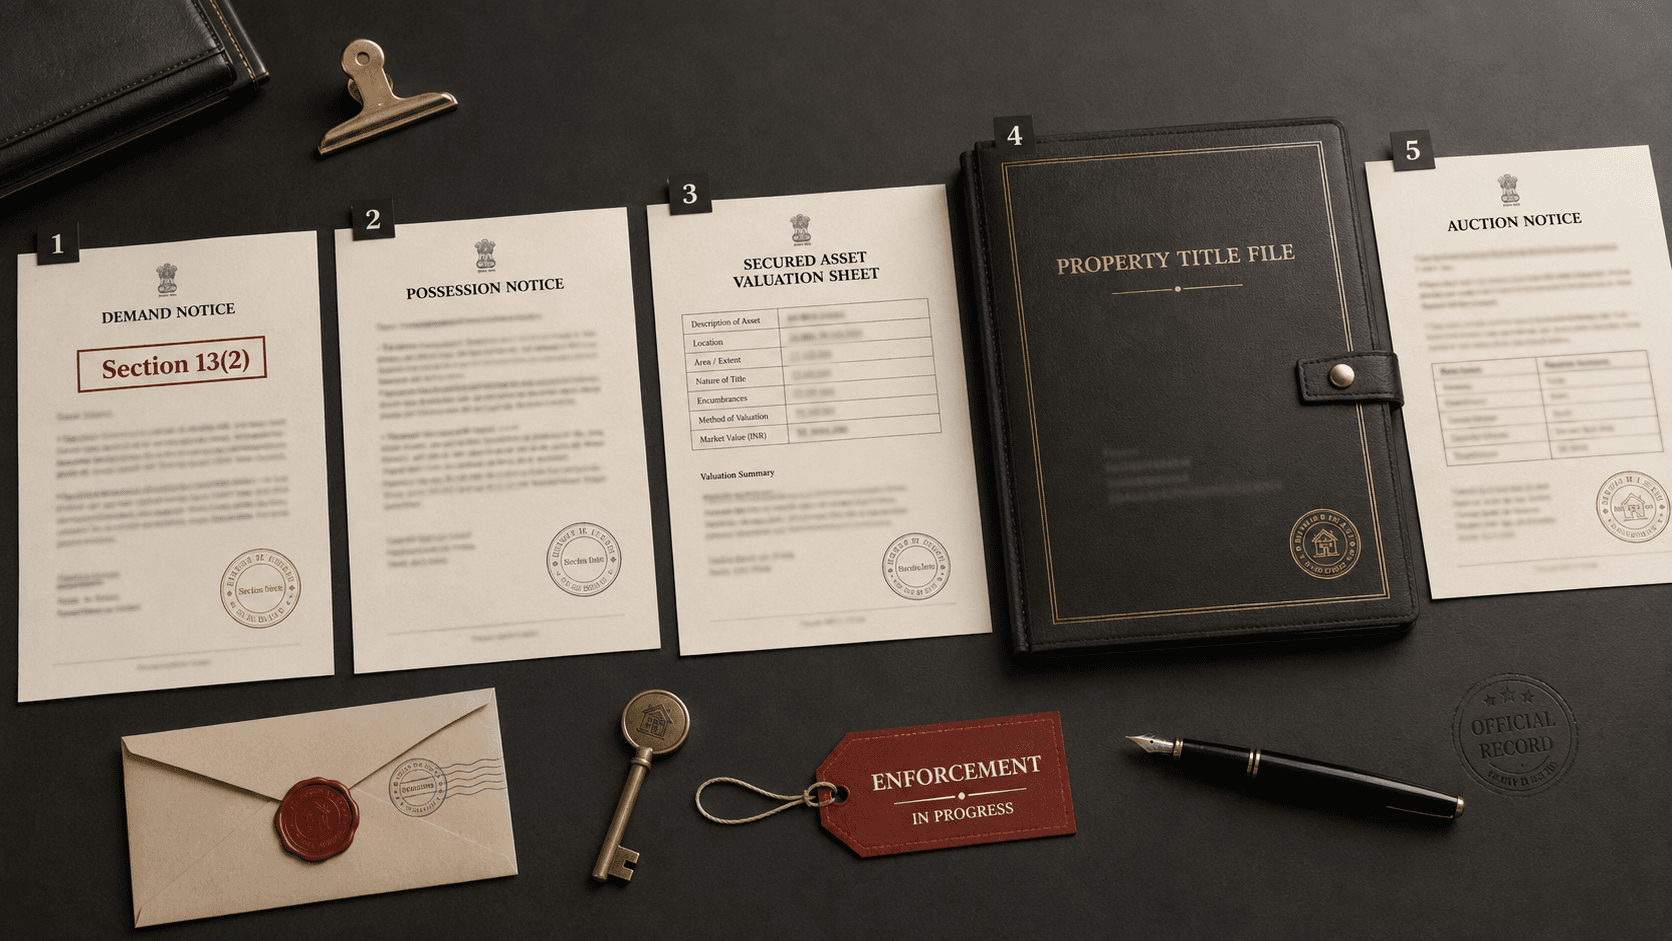
The demand notice under Section 13(2) is the foundation of the enforcement process. Where the borrower has defaulted and the account has been classified as a non-performing asset, the secured creditor may call upon the borrower to discharge the secured liability in full within sixty days from the date of the notice. The notice must state the amount payable and identify the secured assets proposed to be enforced in the event of non-payment.
The amount claimed should be supported by the loan account, interest calculations and contractual provisions. Material inconsistencies between the amount stated in the notice and the creditor’s records may provide grounds for challenge. Care should also be taken to describe the secured asset accurately, with reference to the security documents, title records, boundaries, survey particulars and other identifying details.
The notice should be issued by an officer duly authorised under the Act and the Rules and served upon all persons against whom enforcement is proposed, including the borrower and, where appropriate, guarantors and mortgagors. The creditor should preserve proof of dispatch, delivery, publication and any returned communications.
A borrower may submit a representation or objection after receiving the notice. The secured creditor is required to consider it objectively. Where the objection is rejected, the reasons for non-acceptance must be communicated within fifteen days of receipt. The response should address the material issues raised rather than merely reproducing a standard rejection. At this stage, the communication of reasons does not by itself give rise to an application under Section 17 because the statutory remedy ordinarily becomes available only after a measure under Section 13(4) has been taken.
The sixty-day period should also be used commercially. The creditor may evaluate settlement proposals, identify obstacles to possession, conduct preliminary title and occupancy inquiries and prepare the valuation and sale strategy. Negotiations may continue, but any restructuring or settlement discussions should be clearly documented so that they do not unintentionally compromise existing rights or create uncertainty regarding the enforcement timeline.
Classification of the Account
For most credit facilities, classification of the borrower’s account as a non-performing asset is a statutory precondition to the issuance of a notice under Section 13(2). The classification must be made in accordance with the regulatory norms applicable to the particular secured creditor and the nature of the facility. A mere payment default does not dispense with the requirement of a legally sustainable NPA classification where Section 13(2) requires it.
The account records should clearly establish the date of default, the basis of classification and the regulatory framework applied. The creditor should verify whether payments, restructuring arrangements, temporary regularisation or accounting entries made before classification have any bearing on the status of the account.
The NPA classification requirement under Section 13(2) does not apply in the same manner where the borrower has raised funds through the issuance of debt securities. In the event of default, a debenture trustee may enforce the security interest in accordance with Section 13, with necessary modifications and subject to the relevant security documents.
Classification should not be treated as a mechanical internal entry. Because the validity of the subsequent demand notice and possession measures may depend upon it, the creditor should retain the sanction documents, account statements, default records, regulatory classification note and internal approvals forming the basis of the NPA decision.
Possession of Secured Assets
If the borrower does not discharge the liability within the period specified in the demand notice, the secured creditor may take one or more measures under Section 13(4). These include taking possession of the secured assets, with the right to transfer them by lease, assignment or sale, and, in appropriate cases, taking over the management of the borrower’s business.
For immovable property, Rule 8 requires the authorised officer to deliver a possession notice to the borrower and affix it on the outer door or another conspicuous part of the property. The possession notice must also be published in two leading newspapers, including one vernacular newspaper having sufficient circulation in the locality.
The possession process should be carefully recorded through dated photographs, video, inventories, witness details and contemporaneous reports. Any discrepancy in the description of the property, date of possession or publication particulars may become relevant in proceedings before the Debts Recovery Tribunal.
Where voluntary physical possession is not available, the secured creditor may approach the jurisdictional Chief Metropolitan Magistrate or District Magistrate under Section 14. The application must be accompanied by the statutory affidavit addressing the matters specified in the provision, including the creation of security, classification of the account, issuance of the demand notice, consideration of objections and compliance with the Act and Rules. The Magistrate may authorise a subordinate officer to take possession and may use or cause to be used such force as is necessary for securing compliance.
The secured creditor should decide at an early stage whether it intends to proceed on symbolic possession, seek physical possession before sale or pursue both processes in a coordinated manner. Physical possession may improve marketability and price discovery, particularly where the property is occupied or where prospective purchasers may be reluctant to assume possession-related risks.
Claims by tenants, occupants or third-party purchasers require separate examination. Leasehold claims may be scrutinised by the DRT under Section 17(4A), including whether the lease has expired, is contrary to the mortgage terms or was created after receipt of the demand notice. The creditor should therefore investigate possession and occupancy before fixing the sale timetable.
Sale Procedure
The objective of the sale process is not merely to complete an auction but to obtain a legally defensible sale at a commercially reasonable price. Before selling immovable property, the authorised officer must obtain a valuation from an approved valuer and, in consultation with the secured creditor, fix the reserve price. The property may be sold through quotations, public tender, public auction or private treaty, subject to the requirements of the Rules.
The borrower must be served with thirty days’ notice of the proposed sale. In the case of a public auction or public tender, a sale notice must also be published in two leading newspapers, including one vernacular newspaper having sufficient circulation in the locality. The notice should disclose the property description, known encumbrances, the secured debt, reserve price, auction details, earnest money requirements and other material information necessary for a purchaser to assess the nature and value of the property. No sale of immovable property may take place before the expiry of the prescribed thirty-day period.
Disclosure of encumbrances should be based on a current title and public-record investigation. The secured creditor should avoid making unqualified representations that the property is free from all claims unless that position has been properly verified. Known litigation, occupation, statutory dues and title defects may materially affect the reserve price and bidder participation.
The reserve price should reflect a genuine valuation exercise. Where the property has specialised use, restricted access, incomplete construction or occupancy issues, a conventional market valuation may not be sufficient. A second valuation or a revised valuation may be appropriate where there has been substantial delay or a material change in market conditions.
The highest bid remains subject to confirmation by the secured creditor, and a sale below the reserve price cannot ordinarily be confirmed. A below-reserve sale may be undertaken only with the consent contemplated by the Rules. The successful purchaser is required to deposit twenty-five per cent of the sale price, including earnest money already paid, immediately. The balance is ordinarily payable on or before the fifteenth day following confirmation, subject to a written extension permissible under the Rules.
A further statutory consideration arises under Section 13(8). Where the borrower tenders the secured creditor’s entire dues together with the applicable costs, charges and expenses before publication of the notice for public auction, tender, quotation or private treaty, the secured asset must not be transferred and no further step towards the transfer may be taken.
On confirmation of the sale and compliance with the payment terms, the authorised officer may issue the sale certificate. The creditor should maintain a complete sale record containing the valuation, reserve-price approval, possession documents, notices, newspaper publications, bidding records, payment receipts, confirmation decision and sale certificate.
If the sale proceeds are insufficient, Section 13(10) permits the secured creditor to seek recovery of the balance through the DRT or another competent forum, as applicable. The creditor may also proceed against guarantors or pledged assets without first exhausting the secured asset covered by the SARFAESI proceedings.
Remedies Before the Debts Recovery Tribunal
Any person, including the borrower, who is aggrieved by a measure taken under Section 13(4) may file an application under Section 17 before the jurisdictional Debts Recovery Tribunal within forty-five days from the date of the measure. The application is commonly referred to as a securitisation application. It is not an appeal against the demand notice but a statutory examination of the enforcement measures taken by the secured creditor.
The DRT examines whether the creditor’s measures comply with the Act and the Rules. Where the measures are found to be unlawful, the Tribunal may declare them invalid, restore possession or management to the borrower or another aggrieved person and issue such further directions as may be necessary.
Common grounds of challenge include an invalid NPA classification, defects in the demand notice, failure to consider objections, lack of authority, incorrect identification of the secured asset, defective possession proceedings, non-compliance with publication requirements, inadequate valuation, failure to provide the prescribed sale notice, suppression of known encumbrances and irregular confirmation of sale.
From the creditor’s perspective, the best defence is a complete and chronological enforcement record. Every statutory step should be traceable to a document, approval, service report, publication or contemporaneous note. A procedural gap discovered after possession or auction may be difficult to cure retrospectively.
An order passed by the DRT under Section 17 may be challenged before the Debts Recovery Appellate Tribunal under Section 18 within thirty days of receipt. An appeal by the borrower is subject to a deposit of fifty per cent of the debt claimed by the secured creditor or determined by the DRT, whichever is less. The DRAT may, for recorded reasons, reduce the deposit, but not below twenty-five per cent.
Conclusion
The SARFAESI Act gives secured creditors an efficient enforcement mechanism, but the strength of that mechanism depends upon disciplined execution. Defects in classification, notice, possession, valuation or sale may delay recovery, reduce the value of the security or result in the enforcement action being set aside.
A properly planned strategy should combine legal compliance with commercial assessment. The creditor should verify the security and its registration, identify title and possession risks, preserve a complete record, consider borrower objections fairly and choose a sale method suited to the asset and the market.
The effectiveness of enforcement depends on procedural compliance, documentation and a properly planned recovery strategy.
This article provides a general overview and does not constitute legal advice. The applicable statutory provisions, regulatory directions and judicial decisions should be reviewed in light of the facts of each transaction.
Discuss a related matter
ASR LAW advises clients on commercial disputes, financial enforcement, arbitration, insolvency and intellectual-property matters.
Contact the Firm