Banking & Finance
Personal Guarantees in Lending Transactions
A practical examination of personal guarantees in lending transactions, including drafting, invocation, preservation of rights and coordinated recovery against guarantors.
On this page
Introduction
Personal guarantees are frequently used in corporate and commercial lending to strengthen the lender’s recourse beyond the assets of the borrowing entity. Through a guarantee, a promoter, director or other third party agrees to discharge the borrower’s liability if the borrower defaults.
A guarantee can materially improve a lender’s recovery position, but its effectiveness depends upon the language of the guarantee, proper execution, valid invocation and preservation of the lender’s rights against the guarantor. A guarantee should therefore be treated as a substantive credit protection document rather than a routine annexure to the facility agreement.
Key Considerations
Before accepting a personal guarantee, the lender should examine both its legal enforceability and its practical value. The proposed guarantor’s assets, liabilities, existing guarantees, income sources and exposure to other lenders should be assessed. A guarantee from a person with no identifiable or realisable assets may provide limited recovery value even if it is legally valid.
Under Section 126 of the Indian Contract Act, 1872, a contract of guarantee is a contract to perform the promise, or discharge the liability, of a third person in the event of that person’s default. The parties are ordinarily identified as the creditor, the principal debtor and the surety. A guarantee may be oral or written, although institutional lending transactions should invariably use a carefully drafted written instrument.
The guarantee should clearly identify the underlying facilities, the borrower, the secured obligations and the maximum exposure of the guarantor. It should also address interest, default interest, costs, enforcement expenses, renewals, restructuring, amendments and additional facilities.
The lender should separately verify the guarantor’s legal capacity and authority. Where a guarantee is provided by a company, partnership, limited liability partnership, trust or other entity, the constitutional documents, internal approvals and applicable legal restrictions should be reviewed.
The guarantee should be properly stamped in accordance with the law applicable at the place of execution. Where registration is required because the document itself creates or transfers an interest in immovable property, the registration implications must also be examined. A personal guarantee, by itself, should not be confused with a mortgage or another instrument creating security over a particular asset.
Nature and Extent of the Guarantor’s Liability
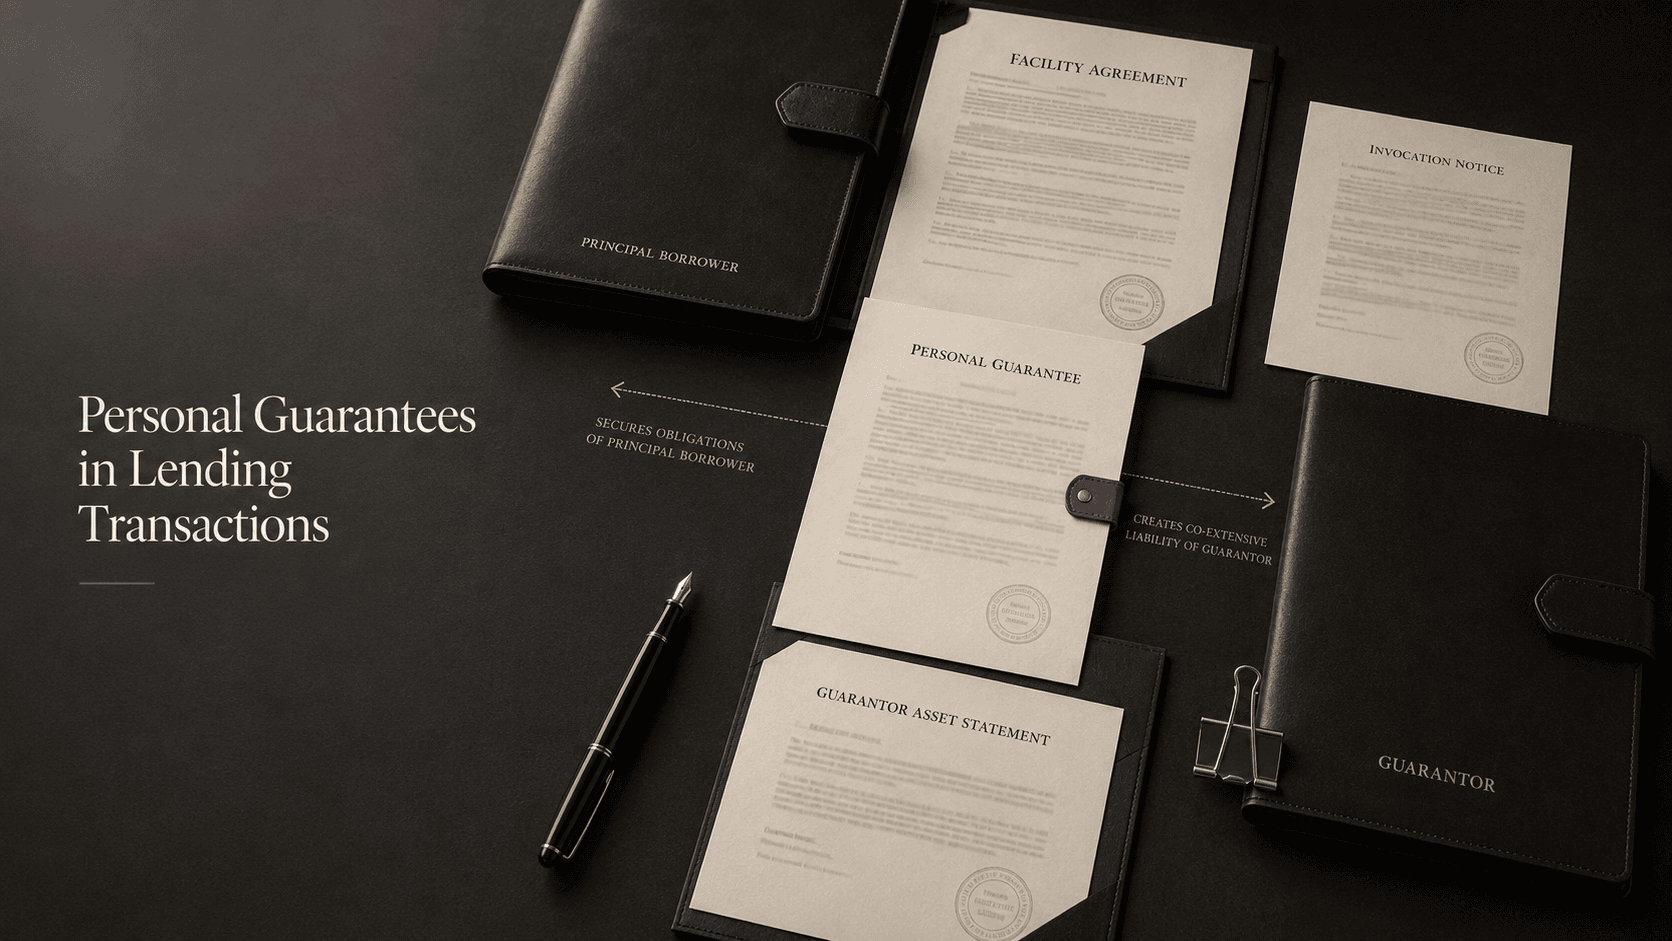
Section 128 of the Indian Contract Act provides that the liability of the surety is co-extensive with that of the principal debtor unless the contract provides otherwise. Accordingly, the extent of the guarantor’s liability ordinarily corresponds with the borrower’s liability, subject to any monetary limit, duration, condition or other restriction contained in the guarantee.
Co-extensive liability means that, upon default and valid invocation, the creditor is not ordinarily required to exhaust its remedies against the borrower or the secured assets before proceeding against the guarantor. The lender may choose the remedy or combination of remedies that is legally and commercially appropriate.
The precise terms of the guarantee nevertheless remain important. A limited guarantee may restrict liability to a specified amount, facility or period. An unlimited guarantee may extend to the entire outstanding liability, including contractual interest and enforcement costs, if the language of the document supports such recovery.
The lender should avoid ambiguity regarding whether the guarantee is transaction-specific or continuing in nature. A continuing guarantee extends to a series of transactions and may remain effective for subsequent drawings or facilities covered by its terms. Where facilities are enhanced, renewed, restructured or materially modified, the lender should determine whether a confirmation or fresh guarantee is required.
Drafting of the Guarantee
The guarantee should contain an unambiguous promise by the guarantor to pay the secured obligations following default. The operative provisions should identify the circumstances in which liability arises and the manner in which the guarantee may be invoked.
A well-drafted guarantee commonly addresses:
- the facilities and obligations covered by the guarantee;
- the maximum amount recoverable, where liability is limited;
- whether the guarantee is continuing and irrevocable;
- the effect of amendments, renewals and restructuring;
- the creditor’s right to grant time or other accommodation to the borrower;
- the effect of the release, substitution or impairment of security;
- the treatment of payments, recoveries and settlements;
- representations concerning the guarantor’s capacity and financial position;
- service of notices;
- governing law, jurisdiction and dispute resolution; and
- the survival of the guarantee until the secured obligations are fully discharged.
The document should distinguish between the lender’s contractual rights against the guarantor and its proprietary rights over secured assets. A personal guarantee creates personal recourse against the guarantor. It does not, without an additional security document, create a charge or mortgage over the guarantor’s property.
Standard-form waivers should not be inserted mechanically. The drafting should reflect the actual transaction, the nature of the facilities and the changes that may reasonably occur during the life of the loan.
Invocation of the Guarantee
Invocation is the formal step through which the lender demands payment from the guarantor following the borrower’s default. Whether a separate demand is legally necessary depends upon the terms of the guarantee and the circumstances in which the liability has been framed to arise. As a matter of enforcement discipline, lenders should ordinarily issue a clear written invocation.
The invocation notice should identify the guarantee, the underlying facility, the event of default and the amount demanded. It should require payment within the period specified in the guarantee or within a reasonable period where no specific period is prescribed.
The amount claimed should be reconcilable with the lender’s account statements and contractual calculations. Where the guarantee is capped, the demand should remain within the agreed limit, while separately addressing recoverable interest or costs where the document permits them.
The lender should serve the notice in accordance with the contractual notice provision and preserve evidence of delivery. Notices may be sent through more than one permitted mode where there is a possibility of avoidance or dispute regarding service.
Care should also be taken not to confuse the invocation of a personal guarantee with the invocation of an independent bank guarantee. A personal guarantee supporting a loan is generally linked to the underlying debt. An unconditional bank guarantee may constitute an independent payment obligation governed substantially by its own terms.
Preservation of Rights Against the Guarantor
A creditor’s conduct after execution of the guarantee may affect the surety’s liability. The Indian Contract Act contains several provisions dealing with circumstances in which a surety may be discharged, including material variations in the underlying contract made without the surety’s consent, release of the principal debtor and conduct impairing the surety’s eventual remedy against the principal debtor.
The lender should therefore examine the guarantee before agreeing to any material amendment, restructuring, substitution of borrower, release of security or compromise with the principal debtor. Broad consent provisions may protect the lender in relation to anticipated changes, but reliance on general wording should not replace a transaction-specific legal review.
Security held by the lender should also be documented and managed carefully. A surety that pays the guaranteed debt may acquire rights against the principal debtor and the benefit of securities held by the creditor, subject to the applicable law. Unauthorised loss or release of security may consequently create disputes concerning the extent of the guarantor’s discharge.
Any settlement with the borrower should expressly address its effect on the guarantee. A lender should distinguish between granting time or contractual forbearance and legally releasing the principal debtor. Settlement documents should reserve rights against guarantors where continued recourse is intended and legally permissible.
The lender should also obtain periodic acknowledgments or confirmations where appropriate, particularly when facilities are renewed or restructured. Limitation should be monitored separately for claims against the borrower and guarantor, with reference to the wording of the guarantee, the date of invocation, acknowledgments and other legally relevant events.
Recovery Proceedings Against the Guarantor
Following default and invocation, the lender may pursue recovery against the guarantor through the forum and procedure applicable to the transaction. Depending upon the lender, the debt, the documentation and the relief sought, the available routes may include proceedings before the Debts Recovery Tribunal, civil or commercial proceedings, arbitration, enforcement of separate security and insolvency proceedings under the Insolvency and Bankruptcy Code, 2016.
Where the guarantee contains a valid arbitration agreement, disputes may be referred to arbitration, subject to questions of arbitrability, jurisdiction and the remedies available to the particular lender.
Banks and financial institutions falling within the Recovery of Debts and Bankruptcy Act, 1993 may seek recovery from borrowers and guarantors before the appropriate Debts Recovery Tribunal where the statutory requirements are satisfied.
A personal guarantor to a corporate debtor may also fall within the personal guarantor framework under the Insolvency and Bankruptcy Code. The statutory scheme applicable to personal guarantors operates separately from the corporate insolvency process, although the proceedings are institutionally coordinated through the adjudicating authority specified by the Code. The current Code, rules and regulations should be reviewed before initiating such proceedings because the personal guarantor framework has undergone legislative and regulatory development.
The Supreme Court has upheld the application of the notified personal guarantor provisions to personal guarantors of corporate debtors. It has also recognised that the approval of a resolution plan for the corporate debtor does not, merely by itself, discharge the personal guarantor from an independently enforceable guarantee. The effect of any resolution plan, settlement or discharge must nevertheless be assessed with reference to its precise terms and the governing law.
The moratorium applicable to a corporate debtor under Section 14 of the Insolvency and Bankruptcy Code does not automatically extend to the personal guarantor merely because the guarantor has guaranteed the corporate debtor’s obligations. Separate insolvency proceedings involving the guarantor may, however, produce their own statutory consequences.
Strategic Enforcement Considerations
The lender should develop an integrated recovery strategy rather than initiating parallel proceedings without coordination. The value, cost, speed and legal effect of each remedy should be assessed.
Relevant considerations include:
- the guarantor’s identifiable assets and income;
- the existence of prior charges, attachments or competing claims;
- the location of the guarantor and assets;
- the limitation position;
- pending proceedings involving the borrower;
- the status of secured assets;
- the possibility of dissipation or transfer of assets;
- the likelihood of settlement;
- the cost and duration of the available proceedings; and
- the effect of recoveries made from the borrower, guarantor or security.
The lender cannot recover more than the total amount legally due merely because it pursues multiple remedies. Recoveries from the borrower, guarantor and secured assets must therefore be properly appropriated and reflected in the outstanding claim.
Early asset investigation is often as important as the legal proceeding itself. Public records, corporate filings, security registrations, litigation records and disclosed financial information may assist in determining whether proceedings against the guarantor are commercially justified.
The lender should maintain a consolidated record containing the facility documents, guarantee, security documents, account statements, default notices, invocation, acknowledgments, settlement communications and details of recoveries from all sources.
Conclusion
A personal guarantee can provide lenders with an important additional source of recovery, particularly where the borrowing entity has limited unencumbered assets. Its value, however, depends upon careful drafting, proper execution, timely invocation and a realistic assessment of the guarantor’s financial position.
Lenders should ensure that the guarantee corresponds with the underlying facility, accommodates contemplated amendments and preserves recourse through the life of the transaction. Material variations, release of security, settlements and insolvency proceedings should be reviewed for their effect on the guarantor’s liability.
The effectiveness of a personal guarantee depends on precise documentation, preservation of contractual rights and a coordinated enforcement strategy.
This article provides a general overview and does not constitute legal advice. The applicable contractual documents, statutes, regulations and judicial decisions should be examined in light of the facts of each transaction.
Discuss a related matter
ASR LAW advises clients on commercial disputes, financial enforcement, arbitration, insolvency and intellectual-property matters.
Contact the Firm